Coverage of tax responsibility, workers’ comp, liability exposure, and regulatory obligations under co-employment.
PEO risk allocation between parties isn’t straightforward—the co-employment model creates a shared liability structure where some risks transfer to the PEO, some remain with the client company, and others fall into gray areas only clarified when problems arise. Most business owners mistakenly assume signing a PEO agreement offloads most HR liability, but the actual risk distribution depends on specific contract terms, state regulations, and the nature of each compliance issue or claim.
Partnering with a PEO creates a co-employment relationship where legal responsibilities are shared, not transferred. While PEOs handle day-to-day HR functions, business owners remain liable for compliance gaps the IRS or Department of Labor may uncover. Implementing PEO legal oversight best practices helps you maintain necessary visibility into wage claims, worker classification, and benefits administration without micromanaging every decision, protecting your business from unexpected legal e…
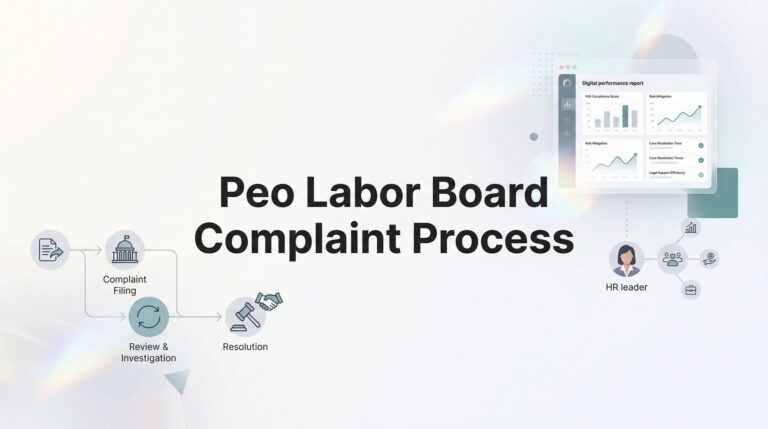
When a labor board complaint arrives while using a PEO, the co-employment relationship creates confusion about who handles what. This guide clarifies the PEO labor board complaint process, explaining how responsibilities are divided between you and your PEO, who responds to regulatory agencies, where liability actually falls, and the critical notification deadlines in your service agreement that could leave you unprotected if missed.
Joining a PEO doesn’t always eliminate workers’ comp collateral requirements—some PEOs require letters of credit or cash deposits worth months of premium, while others require none. This guide explains when and why PEO workers comp collateral requirements vary, what forms they take, and how to evaluate whether a PEO’s collateral structure aligns with your business’s cash flow needs before signing a contract.
When you join a PEO, your workers comp claims frequency doesn’t function like it does under a traditional policy—your claims get pooled with hundreds of other employers, meaning both your individual frequency and the entire pool’s performance affect your costs. This creates a shared risk scenario where high-risk businesses can benefit from a stable pool, while low-risk companies might pay more if the pool’s claims frequency deteriorates, making it essential to understand peo workers comp clai…
Restaurant owners face constant litigation exposure from wage disputes, workplace injuries, and employment claims due to high turnover and tipped workers. This framework shows how to strategically deploy a PEO for restaurants litigation risk mitigation—not just for HR convenience, but as structural defense that builds defensible systems preventing lawsuits before they materialize and strengthening your position when claims arise.
Partnering with a PEO means sharing employer responsibilities like payroll, benefits, and compliance, but you still carry legal and financial exposure if issues arise. This guide covers seven essential PEO internal audit considerations that help business owners verify accuracy, maintain compliance, and protect against costly surprises—from payroll tax verification to benefits administration and regulatory filings—giving you control over a relationship where your company’s reputation and finan…

Before signing with a PEO provider, conduct a thorough PEO state employment law risk review to evaluate how they handle multi-state compliance challenges. Companies operating across states like California, Texas, and New York face vastly different leave laws, wage payment rules, and penalty structures—making your PEO choice either a critical safety net or a major liability exposure. This systematic review process helps you stress-test a provider’s state-specific compliance capabilities before…
Employment lawsuits cost small businesses $125,000-$250,000 to defend, but most companies aren’t properly using their PEO’s compliance infrastructure for protection. This PEO employment litigation prevention guide provides six practical operational steps to structure your co-employment relationship effectively, from documentation systems to termination protocols, helping you leverage the protection you’re already paying for instead of leaving yourself exposed to costly wrongful termination an…
A PEO workers comp risk transfer framework doesn’t eliminate workplace injury liability—it redistributes it between you and the PEO through co-employment. This breakdown explains exactly which workers comp risks transfer to the PEO, which remain your responsibility, and how to evaluate whether a PEO’s structure genuinely reduces your exposure or simply creates an illusion of protection without the sales pitch.
